UOB EVOL card review: 10% on phone and online spend, and what counts as phone
How the UOB EVOL card pays as at 1 Nov 2026: 10% on local online and mobile wallet spend over S$800, the S$80 cap, no FX fee, no annual fee and what earns 0.3%.
- 10% on phone wallet and online spend
- No annual fee from 1 July 2026
- No foreign currency fee
- $800 minimum every statement month
- Caps fill at $300 and $200 of spend
- Physical card taps earn 0.3%
Ethan's own opinion of the card as reviewed below. His full rating is at the end.
The UOB EVOL pays 10% on local online and mobile wallet spend, and 0.3% on most other things. The catch is how you pay: a phone tap and a card tap at the same counter, for the same drink, earn different rates. The bonus also needs $800 of spend in a statement month, and the caps are small.
Here's what it pays and on what, what counts as "mobile contactless", the overseas side, and a worked year you can redo with your own spending.
The UOB EVOL at a glance
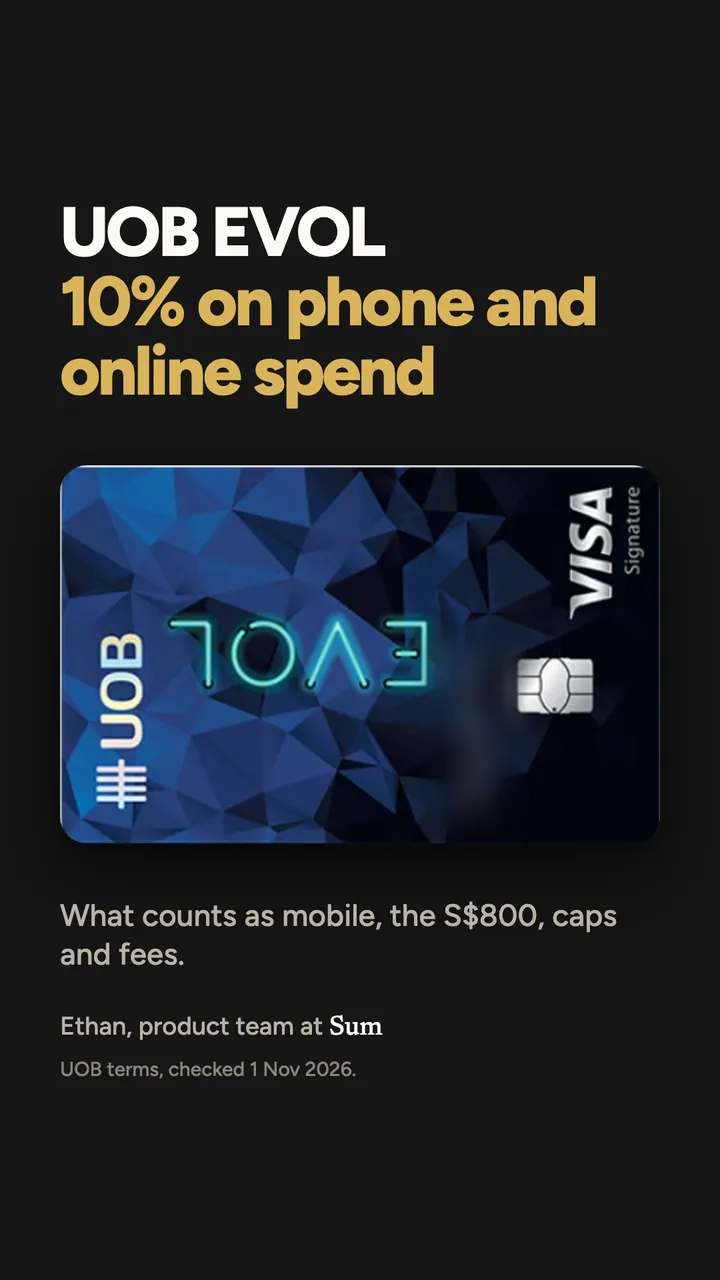
| UOB EVOL Card | |
|---|---|
| Minimum income | $30,000 a year (Singaporeans and PRs aged 55 and under), $15,000 (56 and above), $40,000 (foreigners), as listed on the UOB product page |
| Annual fee | None, principal and supplementary, from 1 July 2026 |
| Minimum spend for the bonus | $800 of eligible spend per statement month |
| Local online and mobile contactless | 10%, capped at $30 a month |
| Selected gym, telco and streaming | 10%, capped at $20 a month |
| Other spend | 0.3%, capped at $30 a month |
| Most a month (local) | $80 |
| Below $800 | 0.3% |
| Overseas, foreign currency | Up to 1% promotion to 31 Dec 2027, no minimum or cap |
| Foreign currency fee | None; 1% on SGD charges processed overseas |
| Statements | eStatements only |
Figures from the EVOL Cashback Programme terms (updated 1 July 2026, Ver 2.2), the FX promotion terms (20 September 2026), the EVOL FAQ (15 Oct 2026) and the UOB product page, checked 1 Nov 2026.
How much cashback does the EVOL give?
Clause 1 of the terms sets three kinds of cashback, all needing at least $800 of eligible transactions in the statement month (clause 3):
| Spend | Rate | Cap a statement month | Bonus spend that fills the cap |
|---|---|---|---|
| Local online and mobile contactless | 10% | $30 | $300 |
| Selected gym, telco and streaming | 10% | $20 | $200 |
| All other spend | 0.3% | $30 | $10,000 |
The total is capped at $80 a statement month (clause 2). If you don't reach $800, you get 0.3% instead (clause 4), which UOB's FAQ (question 7) describes as 0.3% on local transactions, with the overseas promotion still applying.
The caps do most of the work. The 10% on online and mobile spend stops at $300 of it: $300 × 10% = $30. Spending $600 that way still earns $30 on it, which is 5% on the $600.
Cashback is worked out on the statement month's totals, rounded to two decimal places (clause 5), and credited the following month against your next bill (clause 6). Unused cashback is forfeited 2 calendar years after it's awarded, or when the card closes (clause 9). The card doesn't earn UNI$ (clause 27).
Bottom line: the card is built for about $300 by phone wallet or online, up to $200 of telco, gym and streaming, and enough else to reach $800. Past that, extra spending earns 0.3%.
What counts as "mobile contactless", and what doesn't
Clause 18: Local Mobile Contactless Spend means in-store contactless payments with Apple Pay, Samsung Pay, Google Pay and other mobile wallets UOB accepts, processed in Singapore.
So, at the same counter, on the same $1.80 drink: - Phone or watch wallet tap: mobile contactless, 10% (once you've reached $800 that month). - Tapping the physical card: not mobile contactless. It's "other spend", 0.3%. - Wallet used online (say, Apple Pay on a website): online, not mobile contactless, but the same 10% (clause 18).
Local Online Spend is any purchase over the internet, by the system's indicators, processed in Singapore by the merchant or its bank (clause 17). UOB's FAQ adds that in-app purchases count.
Two more rules. Overseas online or mobile wallet spending in a foreign currency counts as overseas spending (clause 20). And the 10% gym, telco and streaming category needs the right merchant code and a named merchant, such as Singtel, StarHub, M1, Netflix, Spotify, Anytime Fitness or ClassPass, processed in Singapore (clause 19).
Assuming you've reached $800 that month:
| Purchase, $10 | How you paid | Cashback |
|---|---|---|
| Lunch at a food court | Phone wallet tap | $1.00 |
| Lunch at a food court | Physical card tap | $0.03 |
| Food delivery app | In-app | $1.00 |
| Netflix | Card on file | $1.00 (gym, telco, streaming) |
Bottom line: every tap of the plastic earns 0.3%.
The $800, and the month that falls short
Say one month comes to $790, with $300 of it by phone wallet. Below the minimum, it's all 0.3%: $790 × 0.3% = $2.37.
The next month comes to $800, with the same $300 by phone wallet: $300 × 10% = $30, plus $500 × 0.3% = $1.50, for $31.50. That's $29.13 more for $10 more spending.
What counts towards the $800 is what earns: retail purchases, minus the exclusions below (FAQ question 9). Supplementary cards' spending counts (clause 7). So does foreign currency spending, converted at UOB's rate and posted in SGD (clause 23).
Bottom line: this isn't a reason to spend $10 more. It's a reason to know where the month stands before it closes.
Overseas: no FX fee, and a promotion
Clause 13 says there are no FX fees on overseas foreign currency spending, whether or not you reach $800. Many cards charge 3.25%. The 1% international processing fee still applies to transactions charged in Singapore dollars but processed overseas (clause 14), so at an overseas terminal, paying in the local currency avoids both.
The overseas cashback comes from a separate promotion (FX promotion terms, 20 September 2026, and FAQ question 6), with no minimum spend and no cap:
| Overseas, foreign currency | To 31 Dec 2026 | 1 Jan to 31 Dec 2027 |
|---|---|---|
| China and Europe | 0.5% | 0.5% |
| Australia | 1% | 0.5% |
| Everywhere else | 1% | 1% |
It sits outside the $80 local cap (FAQ question 8), and it's for the main cardholder's spending only. The main terms set no lasting rate for overseas foreign currency spending (clause 21 leaves it out of "other spend"), so after 31 December 2027 it would earn nothing unless UOB extends the promotion.
On a $2,000 holiday in Japan, paid in yen: $2,000 × 1% = $20 back, and no FX fee. On a card charging 3.25%, the same holiday would cost $2,000 × 3.25% = $65 in fees.
Bottom line: the bigger number overseas is the fee you don't pay, not the cashback. The promotion has an end date, so check the FAQ before a trip in 2028.
The annual fee: none
From 1 July 2026, the EVOL has no annual fee (clause 15), for principal and supplementary cards, with no minimum spend (FAQ question 12). Before that, the fee was waived only with at least 3 purchases a month for 12 months.
Bottom line: there's no fee to earn back, so a quiet month only costs you the bonus, not money.
What doesn't earn cashback, or count to the $800
Clause 22 excludes, as at 1 Nov 2026: Shell and SPC petrol stations; top-ups to payment providers or prepaid accounts, such as GrabPay; utilities, insurance, rent, tax, school and university fees, hospitals, parking, gambling, charities and government services (by merchant category code); payments through AXS, EZ-Link, iPayMy, SingPost SAM, SP Services and SP Digital, and a list of brokers; NETS, instalment plans, cash advances, fees and interest.
Bottom line: utility bills and insurance premiums won't help you reach $800.
How it compares on cashback
Cashback cards with an $800 monthly minimum, from Sum's reading of each bank's terms as at 24 Oct 2026:
| Card | Bonus rate | On what | Monthly cap |
|---|---|---|---|
| UOB EVOL | 10% | Local online and mobile wallet; selected gym, telco, streaming | $80 in all |
| Citi Cash Back | 6% / 8% | Dining and groceries / petrol and private-hire rides | $80 in all |
| OCBC 365 | 6% | Dining, groceries, petrol, land transport | $160 on the bonus categories |
The EVOL's bonus depends on how you pay. The other two depend on what you buy. Each card's exclusions and fees differ.
A worked year
Say Siti is 27 and puts about $850 a month on the card: $280 by phone wallet and online, $90 on her Singtel and Netflix bills, and $480 of everything else, much of it physical card taps. She takes one $2,000 trip to Japan, paid in yen. Made-up example.
| Sum | Cashback | |
|---|---|---|
| Phone wallet and online | $280 × 10% × 12 | $336.00 |
| Telco and streaming | $90 × 10% × 12 | $108.00 |
| Everything else | $480 × 0.3% × 12 | $17.28 |
| Japan trip | $2,000 × 1% | $20.00 |
| Total | $481.28 |
No annual fee and no FX fee, so she keeps that. If she moved $20 a month of card taps to her phone wallet, the first row would reach its $30 cap: $20 × 10% × 12 = $24 more, less the $20 × 0.3% × 12 = $0.72 those taps earned, for $504.56. Moving more adds nothing, because the cap is full.
Bottom line: swap in your own monthly spend and how you pay. The calculator page does the same sums: UOB EVOL on the card rewards calculator.
Three things to remember
- $800 a statement month brings 10% on local online, mobile wallet, and selected gym, telco and streaming spend, up to $80 in all.
- A physical card tap earns 0.3%. Mobile contactless means Apple Pay, Samsung Pay or Google Pay, in a shop, in Singapore.
- No annual fee and no FX fee, with up to 1% back overseas until the end of 2027.
Ethan's rating
Earn rate
- Very low
- Low
- Moderate
- High
- Very high
Effort to earn
- Effortless
- Easy
- Some effort
- Shiong
- Very shiong
Value for the fee
- Way overpriced
- Overpriced
- Fair
- Good value
- Great value
Against other cashback cards
- Bottom
- Below average
- Average
- Above average
- Top
Where it earns
- DiningGood
- GroceriesGood
- TransportGood
- OnlineBonus rate
- TravelLow
- OverseasFair
- Everything elseLow
The bonus follows how you pay (phone or online), not what you buy.
One person's opinion, from the terms in this review. Your own spending decides what a card is worth to you.
Track it in Sum
Import your card statements. The card tracker shows a card's month against its minimum and how full each cap is: have you reached $800, and is the 10% still earning.
One limit. A statement line doesn't always say whether a tap was the phone or the plastic, so Sum's estimate can differ from UOB's for those. The cashback line on the statement is the one that counts.
Ethan
Got something interesting to share?
Something here doesn't match your statement, or UOB changed the terms? Reach out to me at [email protected], or leave your email and I'll write to you.
Questions people ask
How much cashback does the UOB EVOL card give?
With at least S$800 of eligible spend in a statement month: 10% on local online and mobile contactless spend (capped at S$30), 10% on selected gym, telco and streaming merchants (capped at S$20), and 0.3% on other spend (capped at S$30). That's up to S$80 a month. Below S$800, it's 0.3%.
Does tapping the physical UOB EVOL card earn 10%?
No. Mobile contactless means in-store payments with Apple Pay, Samsung Pay or Google Pay processed in Singapore. Tapping the plastic card counts as other spend and earns 0.3%.
Does UOB EVOL charge a foreign currency fee?
No. The terms say there's no FX fee on overseas foreign currency spend. A 1% fee still applies to Singapore dollar charges processed outside Singapore.
Does UOB EVOL earn cashback overseas?
Under a promotion to 31 Dec 2027: 1% on most foreign currency spend, 0.5% in China and Europe, and in Australia 1% in 2026 and 0.5% in 2027, with no minimum and no cap.
Is there an annual fee on UOB EVOL?
No. From 1 July 2026, the annual fee is waived for principal and supplementary cards, with no minimum spend.
Does a GrabPay top-up count towards the UOB EVOL S$800?
No. Top-ups to wallets and prepaid accounts, and other excluded transactions, earn nothing and don't count towards the S$800.
Try the numbers yourself

Sum is launching in Singapore soon.
Your banks, cards, CPF and HDB flat, added up into one net worth. Statements sorted, card caps tracked, bills remembered.
Ethan · Product team, Sum
Ethan is on Sum's product team in Singapore. Financial planning and investing took care of Ethan's own money long ago, so this isn't for the pay. The economy right now is rough on Singaporeans, and we are grateful Ethan is determined to alleviate some of this pain here at Sum.
If we listed a wrong number, or you caught a term that changed before we did, email Ethan at [email protected].
Sources: UOB: Terms and Conditions Governing UOB EVOL Card Cashback Programme, updated 1 July 2026, Ver 2.2 (PDF); UOB: EVOL Card FAQs, updated 15 Oct 2026 (PDF); UOB: EVOL Card up to 1% cashback on FX spend promotion T&C, updated 20 September 2026 (PDF); UOB: EVOL Card.
Any app screens shown use sample data, not a real person's. Sum is free to start; some features need a paid plan.
Information only, not financial advice.