UOB Absolute Cashback card review: where the 1.7% applies, and where it's 0.3%
How the UOB Absolute Cashback card pays as at 1 Nov 2026: 1.7% with no cap, the bills that earn 0.3%, insurance, the contactless bonus, fee and a worked year.
- 1.7% on everything, no cap or minimum
- Insurance premiums earn the full rate
- Worked out on monthly totals
- Utilities, medical and school fees earn 0.3%
- Fee not waived after the first year
- Amex, so not every shop takes it
Ethan's own opinion of the card as reviewed below. His full rating is at the end.
The UOB Absolute Cashback is a flat-rate card: 1.7% on almost everything, with no minimum and no cap. The catch is a published list of merchant codes that earn only 0.3%, and an annual fee from the second year.
Here's what it earns, which bills earn what, what it costs, and a worked year you can redo with your own bills.
The UOB Absolute Cashback card at a glance
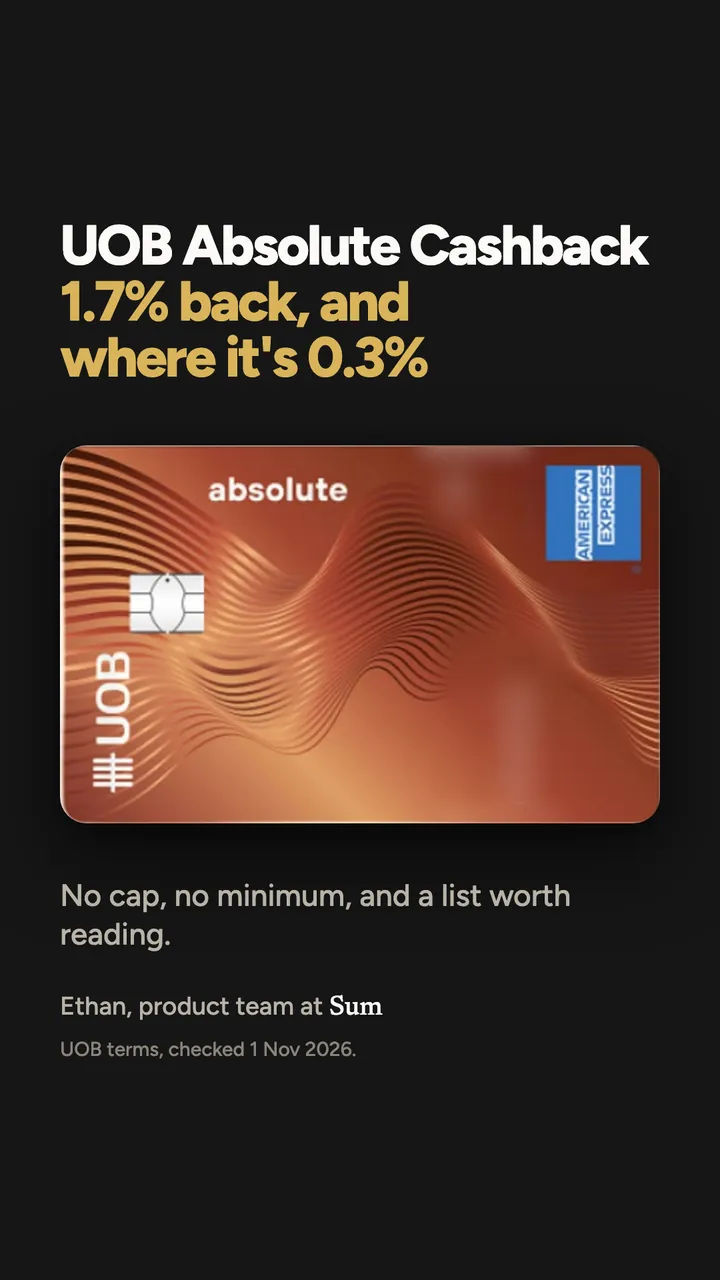
| UOB Absolute Cashback American Express Card | |
|---|---|
| Minimum income | $30,000 a year (Singaporeans and PRs aged 55 and under), $15,000 (56 and over), $40,000 for foreigners; age 21 and over |
| Annual fee | $196.20 including GST, first year waived |
| Supplementary card | First one free, then $98.10 each |
| Local and overseas spend | 1.7% |
| Listed merchant codes and Grab top-ups | 0.3% |
| Contactless bonus | An extra 0.3%, 4 Aug 2026 to 31 Jan 2027 |
| Minimum spend or cap | None |
| How it's paid | Worked out on the statement month, credited in the next statement |
Figures from the card's terms (updated 4 August 2026, Ver 3.0) and the UOB product page, checked 1 Nov 2026.
How much cashback does the UOB Absolute Cashback card give?
Clause 1(i) of the terms sets 1.7% on local and overseas card transactions, with the exceptions below. No minimum spend (clause 1(v)), no cap (clause 1(vi)).
Clause 1(vii) says cashback is calculated on the total of each type of transaction in a statement month, rounded to two decimal places. Not per purchase.
UOB's example on the product page: $99 × 1.7% = $1.683, credited as $1.68.
That protects small purchases. Thirty kopis at $1.40 is $42, and $42 × 1.7% = $0.714, so $0.71. A card that rounds each purchase could pay noticeably less.
Cashback is credited in the next statement and reduces that bill (clause 1(viii) and (ix)). It can't be withdrawn or count towards your minimum payment. Cancel the card and unused cashback is forfeited (clause 1(xiii)). The card earns no UNI$ or other UOB points (clause 2(vi)).
It's an American Express card, and not every shop or biller accepts Amex.
Bottom line: the rate you see is close to the rate you get. The bigger question is whether your usual shops take Amex.
Which payments earn only 0.3%?
Clause 1(i)(c) lists what earns 0.3%, by merchant category code (MCC), the four-digit code a shop's bank gives it to say what kind of business it is. From 4 September 2026, the list applies overseas as well as in Singapore.
| Type of merchant | Codes |
|---|---|
| Schools, colleges, dance studios | 7911, 8211 to 8299 |
| Tax, government and postal services | 9311, 9399, 9402 |
| Doctors, dentists, opticians, hospitals, pharmacies and medical supplies | 5047, 5122, 5912, 5975, 8011 to 8099, 8062 |
| Utilities | 4900 |
| Rent paid to property agents and managers | 6513 |
| Pet shops and vets | 0742 |
| Charities | 8398 |
| Funeral, advertising, employment agencies, consulting, shopping services, professional services | 7261, 7311, 7361, 7392, 7278, 8999 |
| Grab mobile wallet top-ups | (by type of transaction) |
A pharmacy counts here if it's coded as one (5912), so a purchase at a chain pharmacy may earn 0.3% even if you bought shampoo.
Bottom line: this list is where the headline rate changes.
Common household bills, line by line
What each bill would earn on this card, from the terms as at 1 Nov 2026:
| Bill | How it's usually coded | Rate on this card |
|---|---|---|
| SP Services (electricity, water, gas) | Utilities, 4900 | 0.3% |
| Internet and mobile | Telecoms, not on the 0.3% list | 1.7% |
| Insurance premiums | Insurance, not on the 0.3% list or the exclusions | 1.7% |
| S&CC to the town council | Depends on how the town council's payment is coded | 1.7%, or 0.3% if coded as a government service |
Two stand out. Insurance: many cards exclude premiums entirely. Here they're neither excluded nor on the 0.3% list, so a premium earns the full 1.7%, as long as the insurer accepts American Express. A $1,800 yearly premium earns $1,800 × 1.7% = $30.60.
Utilities: a $150 SP Services bill earns $150 × 0.3% = $0.45, not $150 × 1.7% = $2.55.
S&CC depends. If the town council's card payment is coded as a government service (9399), it earns 0.3%. Paid by GIRO from a bank account, as many households do, it isn't a card payment at all.
Bottom line: the code on the statement decides the rate, not the name of the bill.
What earns nothing
Clause 1(iv) lists what earns no cashback at all: NETS payments, instalment plans and SmartPay, cash advances, UOB's own fees and charges, personal loans, balance and fund transfers, and anything cancelled, refunded or reversed. A refund also takes back the cashback it earned (clause 2(i)).
Bottom line: a purchase converted into an instalment plan stops earning.
The contactless bonus until 31 January 2027
From 4 August 2026 to 31 January 2027, UOB pays an extra 0.3% on contactless spending, locally and overseas, on top of the 1.7%. The product page says there's no limit on this bonus.
So $200 tapped in a month earns $200 × 2% = $4.00 instead of $200 × 1.7% = $3.40. That's $0.60 more.
Bottom line: 0.3 cents per dollar, for a few more months. It isn't a reason to change how you pay.
Overseas spending and the foreign currency fee
The 1.7% also applies to overseas card transactions, defined as processed outside Singapore (clause 1(ii)(b)). A purchase from an overseas website can count even if you never left home.
UOB's foreign currency fee is larger than the cashback: 3.25% when we checked the banks' fee schedules on 15 Oct 2026. On a $1,000 hotel bill, that's $1,000 × 3.25% = $32.50 in fees against $1,000 × 1.7% = $17.00 back.
Bottom line: the 1.7% softens the fee. It doesn't pay for it. Check UOB's current fee before a trip.
The annual fee, and what it takes to earn it back
The principal card's fee is $196.20 including GST, waived for the first year. The product page doesn't list a spending-based waiver after that.
At 1.7%, earning back $196.20 takes $196.20 ÷ 1.7% = $11,541 of spending in a year.
The fairer comparison is a card with no fee. The Trust Freedom pays 1.5% on local spending in its unlimited cashback mode with no annual fee. The gap is 1.7% − 1.5% = 0.2%, so the fee is covered only once $196.20 ÷ 0.2% = $98,100 of local spending a year goes on the card. That changes if your spending includes things one card pays on and the other doesn't, like insurance premiums.
Bottom line: the headline rate and the fee belong in the same sum.
How it compares on cashback per $1
Flat-rate cashback cards with no minimum spend, as at 24 Oct 2026, from each bank's terms:
| Card | Local | Foreign currency | Insurance premiums | Utilities |
|---|---|---|---|---|
| UOB Absolute Cashback | 1.7% | 1.7% | 1.7% | 0.3% |
| Citi Cash Back+ | 1.6% | 1.6% | Nothing | Nothing |
| OCBC INFINITY Cashback | 1.6% | 1.6% | Nothing | Nothing |
| Amex True Cashback | 1.5% | 1.5% | 1.5% | 1.5% |
| StanChart Simply Cash | 1.5% | 1.5% | Nothing | Nothing |
| Trust Freedom (unlimited cashback mode) | 1.5% | 0.5% | Nothing | Nothing |
Fees, foreign currency charges and how each bank rounds differ, so the rate is only the first line of the comparison.
A worked year
Say Jun Hao is 36, recently moved into a resale flat, and puts all his regular spending on the card. Made-up example.
| Each month | Sum | Cashback |
|---|---|---|
| Everyday spending | $1,230 × 1.7% | $20.91 |
| Internet and mobile | $120 × 1.7% | $2.04 |
| SP Services | $150 × 0.3% | $0.45 |
| Each month | $23.40 |
Over a year that's $23.40 × 12 = $280.80. Add a $2,400 yearly insurance premium: $2,400 × 1.7% = $40.80. Total: $321.60.
In the first year there's no fee, so he keeps all of it. From the second year, $321.60 − $196.20 = $125.40. If his insurer didn't take American Express, the $40.80 would go, and he'd be left with $84.60.
The contactless bonus adds a little while it runs: if $600 a month of his everyday spending is tapped, that's $600 × 0.3% = $1.80 a month until 31 January 2027.
Bottom line: swap in your own bills and spending, and check which are utilities or medical. The calculator page does the same sums for a few typical months: UOB Absolute Cashback on the card rewards calculator.
Three things to remember
- 1.7% on almost everything, locally and overseas, no minimum and no cap, worked out on monthly totals.
- Utilities, medical, schools, government services, rent to agents and Grab top-ups earn 0.3%. Insurance premiums earn the full 1.7%.
- The $196.20 fee applies from the second year. It belongs in the same sum as the cashback.
Ethan's rating
Earn rate
- Very low
- Low
- Moderate
- High
- Very high
Effort to earn
- Effortless
- Easy
- Some effort
- Shiong
- Very shiong
Value for the fee
- Way overpriced
- Overpriced
- Fair
- Good value
- Great value
Against other cashback cards
- Bottom
- Below average
- Average
- Above average
- Top
Where it earns
- DiningFair
- GroceriesFair
- TransportFair
- OnlineFair
- TravelFair
- OverseasLow
- Everything elseFair
One person's opinion, from the terms in this review. Your own spending decides what a card is worth to you.
Track it in Sum
Import your card statements. The card optimiser reads each purchase's merchant the way the terms do, so an SP Services bill shows up at 0.3% and a premium at 1.7%. Bill reminders keep each due date in one place. Nothing on Sum moves money. It only reads what's there.
Ethan
Got something interesting to share?
Something here doesn't match your statement, or UOB changed the terms? Reach out to me at [email protected], or leave your email and I'll write to you.
Questions people ask
How much cashback does the UOB Absolute Cashback card give?
1.7% on local and overseas spend, with no minimum spend and no cap, and 0.3% on a list of merchant codes such as utilities, schools, medical, government services and Grab wallet top-ups.
Does the UOB Absolute Cashback card earn on insurance premiums?
Insurance isn't on the card's 0.3% list or its exclusions as at 1 Nov 2026, so premiums charged to it earn 1.7%, where the insurer accepts American Express.
Does the UOB Absolute Cashback card earn on SP Services bills?
Utilities (merchant code 4900) earn 0.3%, not 1.7%.
Is there a cap on UOB Absolute Cashback?
No. The terms set no minimum spend and no cap on cashback.
What is the UOB Absolute Cashback annual fee?
$196.20 including GST for the principal card, waived for the first year. The first supplementary card is free.
What is the UOB Absolute Cashback contactless bonus?
An extra 0.3% on contactless spend, locally and overseas, from 4 Aug 2026 to 31 Jan 2027, with no cap, on top of the usual 1.7%.
Try the numbers yourself

Sum is launching in Singapore soon.
Your banks, cards, CPF and HDB flat, added up into one net worth. Statements sorted, card caps tracked, bills remembered.
Ethan · Product team, Sum
Ethan is on Sum's product team in Singapore. Financial planning and investing took care of Ethan's own money long ago, so this isn't for the pay. The economy right now is rough on Singaporeans, and we are grateful Ethan is determined to alleviate some of this pain here at Sum.
If we listed a wrong number, or you caught a term that changed before we did, email Ethan at [email protected].
Sources: UOB: Terms and Conditions Governing UOB Absolute Cashback Card, updated 4 August 2026, Ver 3.0 (PDF); UOB: Absolute Cashback Card.
Any app screens shown use sample data, not a real person's. Sum is free to start; some features need a paid plan.
Information only, not financial advice.